



Categories
- Case Study (12)
- Industrial Building (5)
- ESG (28)
- Fit-Out (3)
- News (61)
- Interior Architecture (11)
- Architecture (24)
- Office (51)
- Studio Alliance (28)
- History (3)
- Design (22)
- Technology (15)
- Artificial Intelligence (AI) (5)
In 2026, the European office market is being shaped by a cautious investment environment, limited new supply and occupier demand shifting towards high quality workplaces. While total leasing activity has slowed in some markets, demand for centrally located, energy efficient offices with high technical standards remains strong. This is creating a clear performance gap between older and next generation offices, even within the same city.
The European office market did not experience uniform growth during the first half of 2026. Economic uncertainty and a decline in large transactions limited overall leasing activity, while corporate demand for high quality offices remained resilient.
According to BNP Paribas Real Estate’s Q2 2026 review of the European office market, total office leasing activity across 18 major European markets reached 3.64 million square metres during the first half of the year. This represented a 9% decline compared with both the same period in 2025 and the five year averag
Vacancy rates, however, vary considerably depending on the location and quality of the office. According to Savills’ Q2 2026 research , the average office vacancy rate across Europe stood at 9.4%, while the rate fell to 4.9% in central business districts and approximately 2% for the highest quality prime offices in central locations.
These figures reveal the main divide within the market. Although overall office supply may appear sufficient, the number of available spaces that meet occupiers’ expectations for location, technical infrastructure and sustainability standards remains limited.

Although signs of recovery are emerging in European office investment, investors remain selective. According to Cushman & Wakefield data , office investment volumes across Europe reached €22 billion in the first half of 2026. This figure was only 1% lower than during the same period last year.
Investor interest is particularly concentrated on properties with the following characteristics:
High financing and construction costs are leading investors to approach new development decisions more cautiously. As a result, refurbishing existing buildings, improving their energy performance and adapting them to current occupier expectations are becoming increasingly important investment options.
Older office buildings in central locations can be brought back to the market through comprehensive refurbishment. A well planned transformation can increase a building’s rental potential while also reducing resource consumption compared with constructing a new property.
Companies are not simply looking for larger or newer offices. They are prioritising spaces that encourage employees to come into the office, support corporate culture and help control operational costs.
According to Cushman & Wakefield’s research, Grade A offices accounted for 51% of European leasing activity during the first half of 2026. The vacancy rate within this segment remained at just 3.3%. Over the same period, prime office rents increased by an annual average of 4.6%.
This development shows that the flight to quality trend is continuing in 2026. Even when companies lease less space, they may be willing to pay higher rents for offices in the right location that offer strong energy performance and support different ways of working.
Leasing activity increased in markets such as Berlin and Munich, while large scale transactions remained more limited in some other European cities. The European office market should therefore be assessed by city, submarket, building grade and accessibility rather than through a single overall average.
Hybrid working has not removed the importance of the office. Instead, it has changed expectations around location. When employees come into the office on specific days of the week, ease of access becomes even more important. Areas with strong public transport connections, nearby social amenities and convenient access to everyday services are becoming increasingly influential in leasing decisions.
The slowdown in new office development is creating supply pressure within the high quality segment. Even when overall vacancy rates appear high, the number of centrally located, technically up to date and ready to occupy offices may remain limited.
This is encouraging companies to plan relocation decisions earlier, while investors are focusing more closely on the refurbishment potential of existing buildings.
The high cost of developing new buildings is making the transformation of existing offices more valuable. Upgrading mechanical and electrical systems, reducing energy consumption, creating more flexible interior layouts and improving shared spaces can strengthen an older building’s position in the market.
To see how an existing headquarters building can be refurbished in line with user needs and sustainability goals, explore our Enerjisa Üretim Headquarters Refurbishment Project.
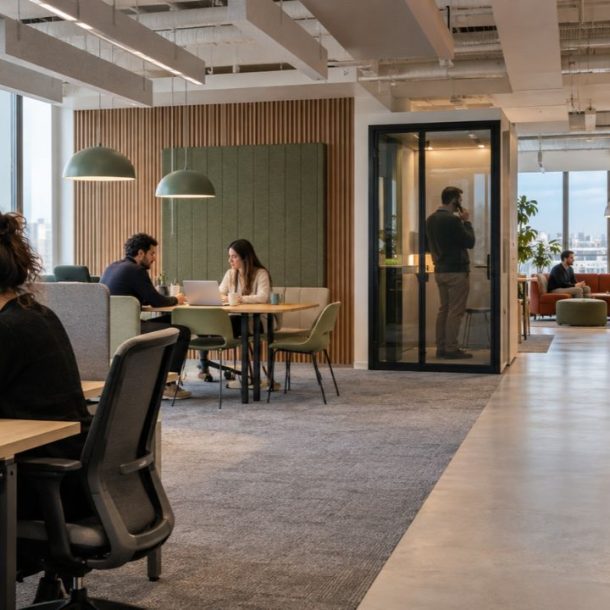
Under hybrid working models, offices are moving away from layouts based on fixed rows of desks. Different spatial options are now required for focus, meetings, social interaction and teamwork.
Employees often come into the office on the same days. As a result, the need for sufficient meeting and collaboration spaces continues even when the total number of employees using the office decreases. Decisions to reduce office space should therefore be based not only on headcount but also on occupancy patterns and workplace scenarios.
Monitoring energy consumption, tracking occupancy data and managing HVAC systems according to actual use are important for both operational costs and sustainability targets.
Smart building systems are no longer viewed simply as technological features. They are increasingly considered part of the infrastructure that supports a building’s long term value. To learn more about sensors, reservation systems and data driven space management, read our article, Smart Office Design: 7 Technologies Improving Productivity in 2026.

In the 2026 market, selecting the right office involves more than comparing floor area and rent. The building’s suitability for long term use and the investment required to adapt it should also be evaluated.
Before making a leasing decision, it may be useful to consider the following questions:
Conducting architectural and technical assessments during the early stages of the leasing process allows potential costs to be estimated more accurately. This makes it possible to select an office that meets current requirements while also adapting to the company’s future working model.
The European office market in 2026 is too divided to be assessed solely in terms of growth or contraction. Despite the slowdown in overall leasing activity, demand and rental growth continue for centrally located, sustainable and high quality offices.
During this period, value creation is not limited to developing new buildings. It also depends on transforming existing spaces to meet evolving working models. Location, flexible space planning, energy efficiency and user experience are now central to the decision making process for both occupiers and investors.
To assess the technical and spatial potential of a new office or transform your existing workplace in line with current requirements, explore Diem’s design and construction services.


